After three decades of falling interest rates, the pendulum has swung. Rising yields have unsettled markets, but for fixed income investors, the opportunity set is looking increasingly attractive. With government bond yields at multi-decade highs, equity risk premia turning negative and credit markets offering compelling income, investors may no longer need to take equity-like risks to generate meaningful portfolio returns. Fixed income is re-emerging as a core portfolio building block, offering investors another source of income and diversification alongside traditional dividend-paying equities and covered-call strategies.
A Generational Shift in Income
For much of the past three decades, falling interest rates provided a powerful tailwind for bond prices, but progressively eroded the income available to investors. The COVID-19 pandemic accelerated this trend, as unprecedented monetary stimulus pushed yields towards historic lows. That era came to an abrupt end when the post-pandemic inflation shock, compounded by geopolitical tensions and surging energy prices, forced central banks to tighten monetary policy.
The consequences are now clear. Australia's 10-year government bond yield climbed to around 5.42% in October, its highest level since 2011, while the US 10-year Treasury yield reached 5.35%, a level last seen in 2002. These moves have been painful for existing bondholders and mortgage holders alike given yields rising across the curve, as higher borrowing costs weigh on household budgets, corporate financing and equity valuations.
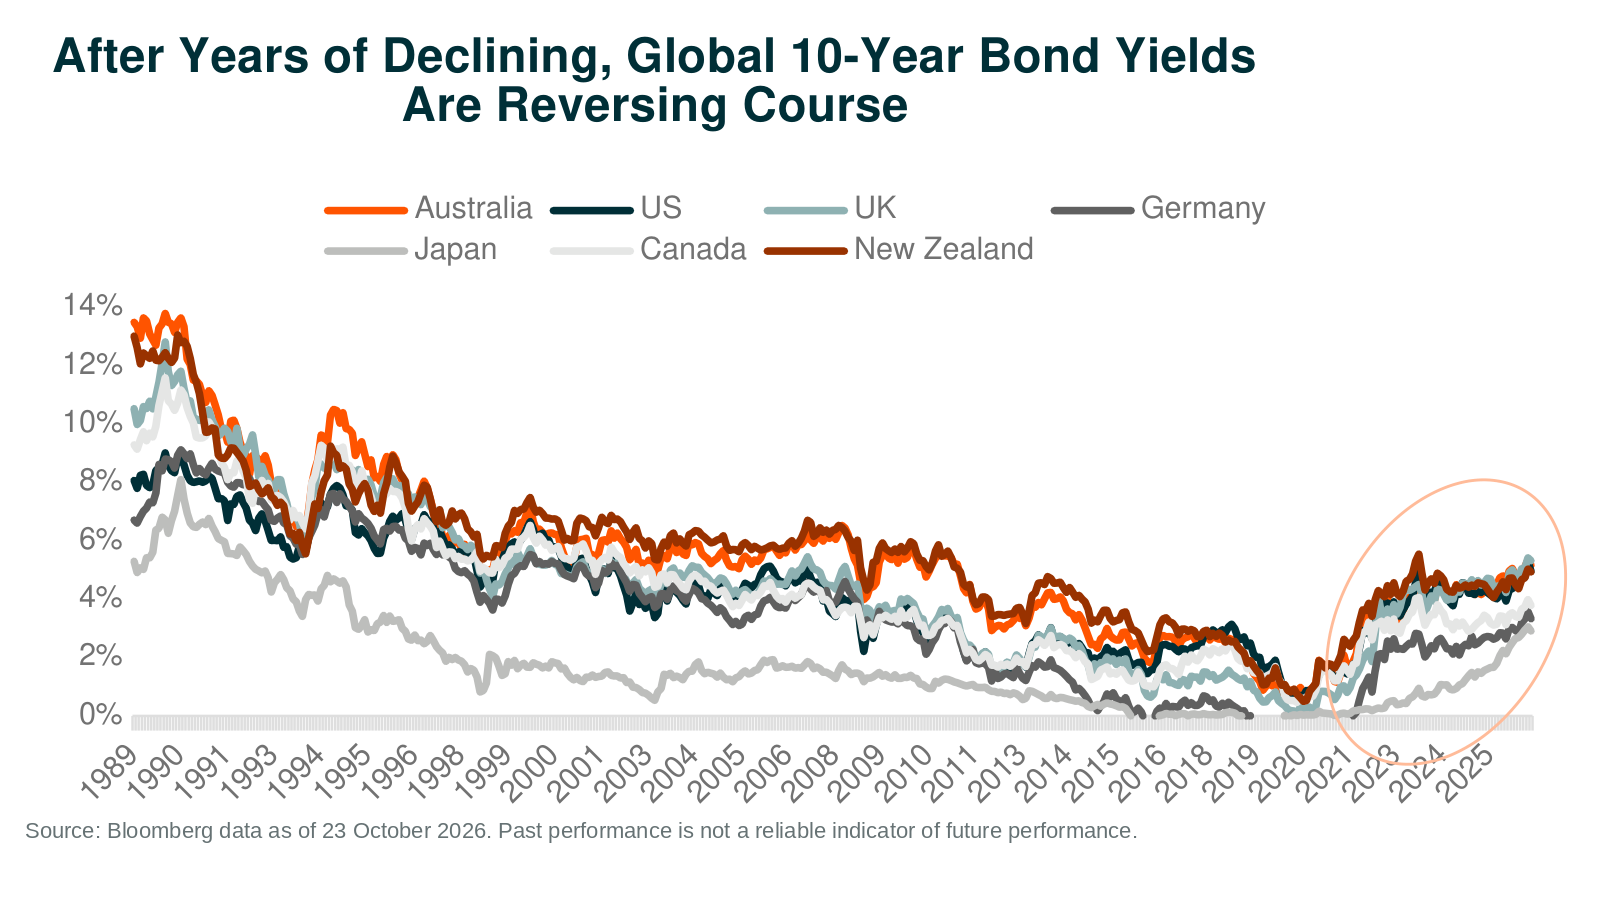
Yet what is bad news for borrowers can be good news for investors lending capital. Higher yields mean investors entering the market today can lock in a substantially higher income stream than was available for much of the previous decade. Importantly, fixed income is more than a tactical opportunity presented by higher yields. It is a core portfolio building block that can provide recurring income, diversification and a potential source of capital stability when equity markets come under pressure.
Bond Arithmetic is Back in Investors' Favour
Unlike equities, where returns depend heavily on earnings growth, valuations and investor sentiment, bond returns have a more tangible starting point: yield. Starting yields are an important indicator of prospective long-term bond returns, although realised outcomes will depend on changes in interest rates, credit spreads and default risk.
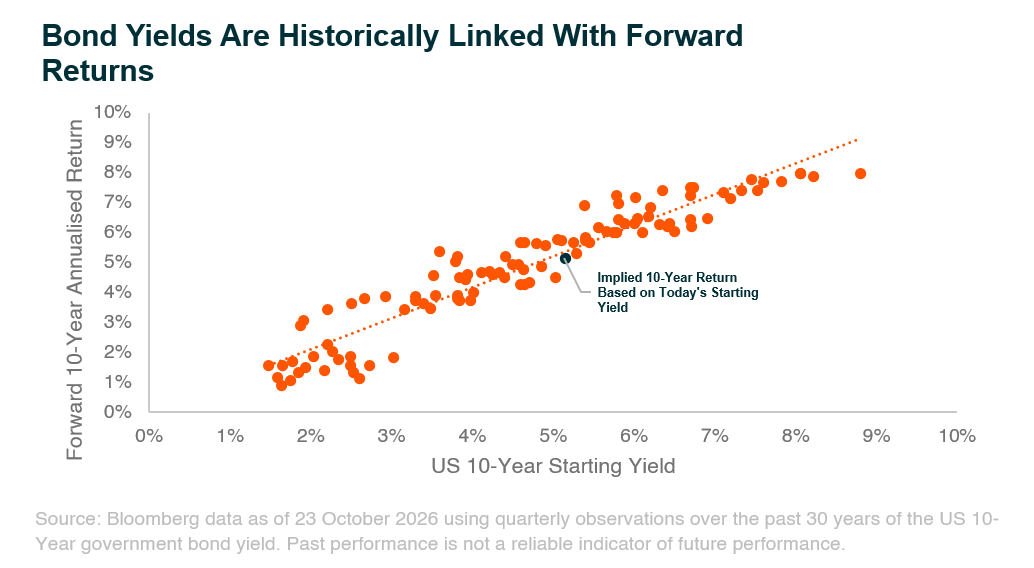
This changes the risk-reward equation considerably. During the COVID era, investors buying government bonds at near-zero yields had little income to cushion further losses and limited scope for capital appreciation. Today, investors are being paid to wait, with the potential to benefit from both income and capital gains.
The equity risk premium, measured as the difference between an equity market's earnings yield and the 10-year government bond yield, has also turned negative in both Australia and the US. In other words, investors are receiving less earnings yield from equities than the yield available from bonds.
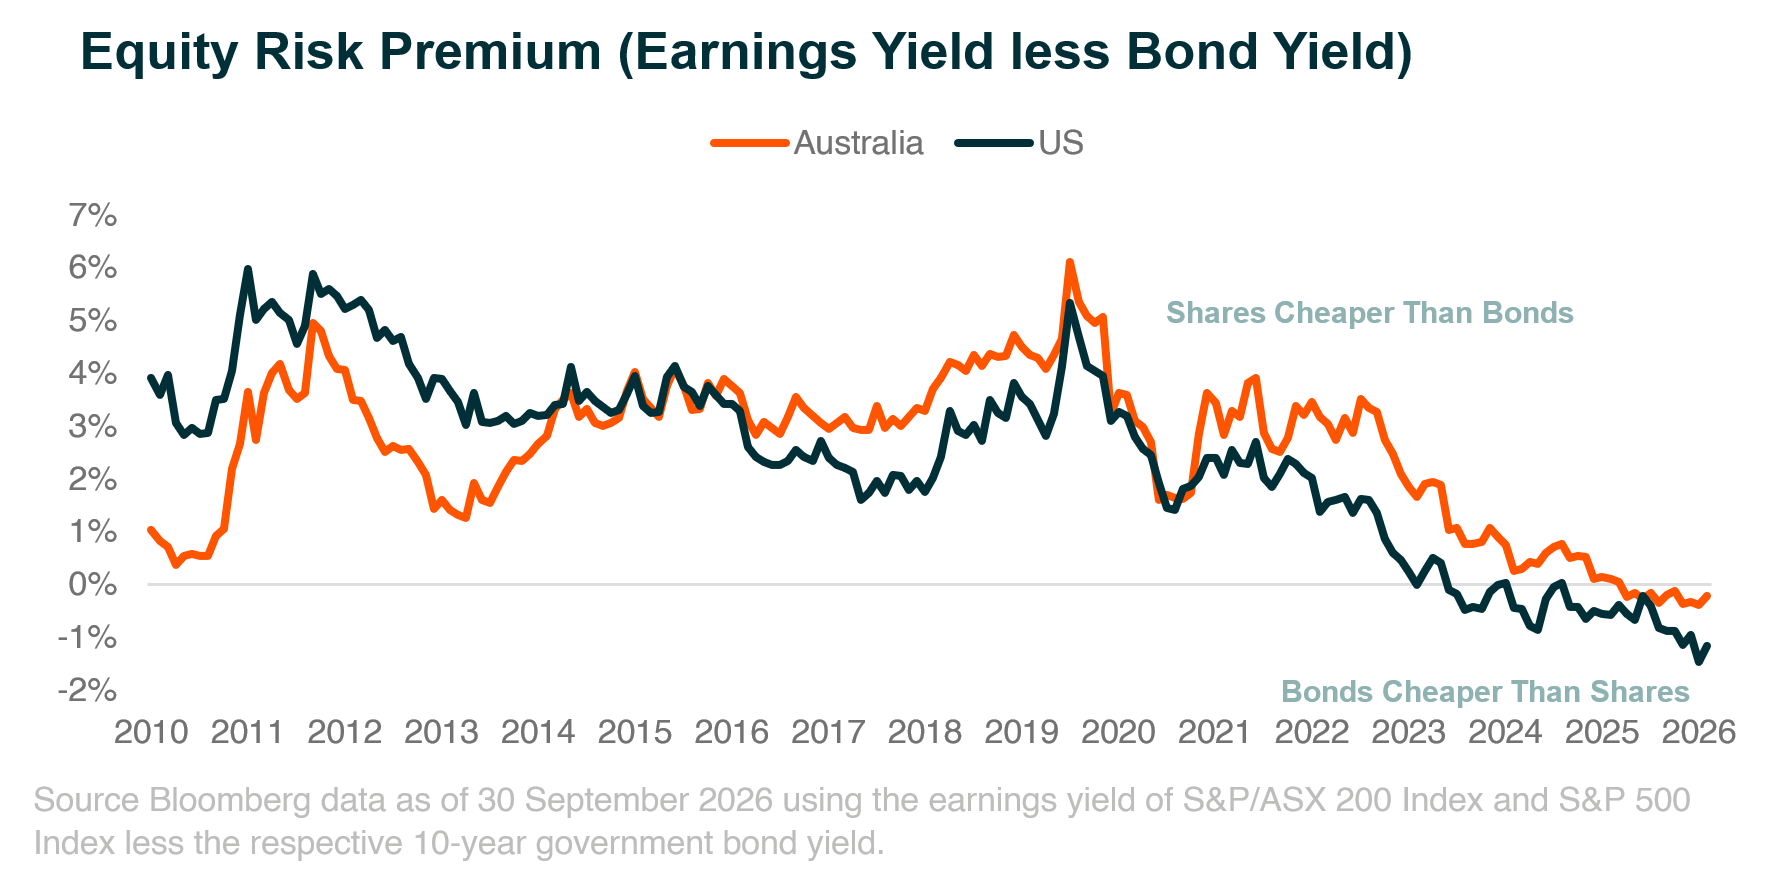
This is not a signal to abandon equities. Earnings yields are not the same as guaranteed returns, and equities offer potential earnings growth that bonds do not. However, it does challenge the assumption that investors must take on equity risk to achieve attractive returns.
The Case For Looking Again At US Treasuries
US government bonds present a particularly interesting opportunity. Despite being the world's largest and most liquid government bond market, US Treasuries have been an unpopular allocation among Australian ETF investors, with concerns around US fiscal deficits, rising debt issuance and currency exposure contributing to investor caution and over $250 million dollars in outflows from Australian-listed US Treasury ETFs over the past year1.
These concerns are legitimate. Persistent inflation, elevated government borrowing and uncertainty around the path of monetary policy could keep yields higher for longer. However, much of this pessimism is already reflected in market pricing, and the recent sell-off has materially improved the income available to investors.
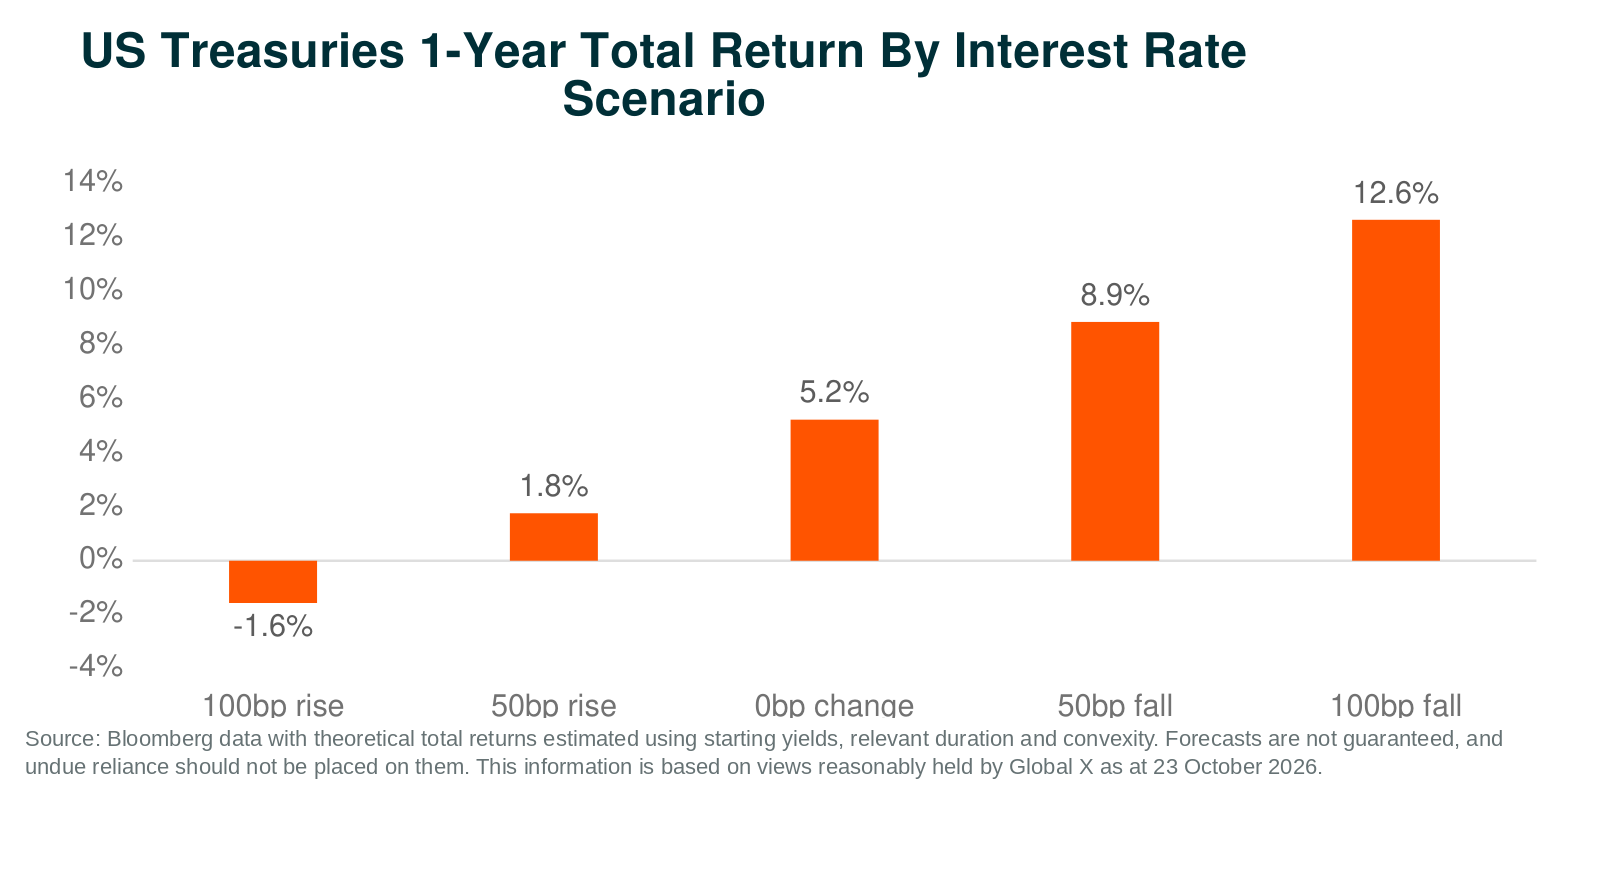
The opportunity is increasingly asymmetric. If inflation moderates and yields retreat from current levels, longer-duration bonds could deliver meaningful capital gains alongside their income. Conversely, if yields rise further, higher starting yields provide a stronger foundation for prospective returns if existing fixed-rate bonds experience capital declines. In other words, today's elevated yields provide a larger income cushion to absorb potential capital losses if yields rise further, while creating meaningful capital appreciation potential if yields eventually decline.
US Treasuries can also play a valuable role in portfolio construction, providing exposure to a different economic and monetary environment from Australian assets. There is also an interesting corporate dimension. Major US hyperscalers are investing heavily in artificial intelligence infrastructure, with debt markets increasingly providing a source of funding for this capital expenditure. Investors can access this broader ecosystem through US credit markets, by investing in ETFs such as the Global X USD Corporate Bond (Currency Hedged) ETF (USIG) and the Global X USD High Yield Bond (Currency Hedged) ETF (USHY). Meanwhile, rising high-yield credit spreads are worth monitoring as questions emerge around the scale and potential returns of AI investment. While spreads remain relatively tight by historical standards, further widening could signal growing concerns around credit risk and create additional volatility for high-yield bond investors.
Australia: Lending to the Banks Instead of Owning Them
Closer to home, Australia's fixed income opportunity is shaped by a different set of challenges. Persistent inflation, weak productivity growth, a slowing property market and softer credit growth create a more complicated outlook for the domestic economy. Yet Australian bank credit remains an attractive source of income. The major banks are well-capitalised institutions, and their debt securities offer investors a way to participate in the income generated by the banking system without relying solely on equity dividends and share price appreciation.
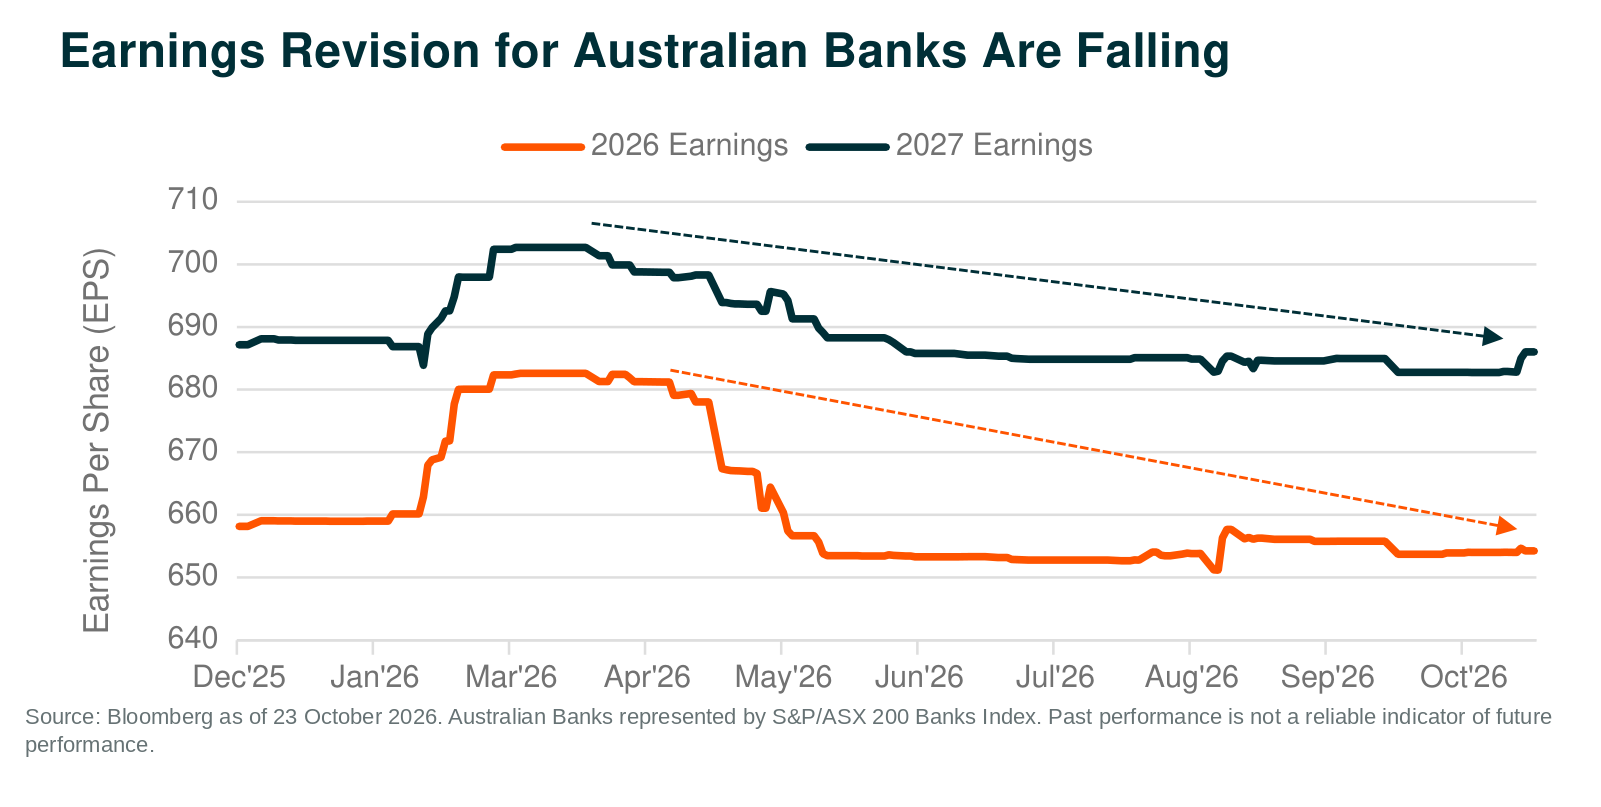
Australian bank equities have had multiple 10% share price corrections so far this year, and remain expensive by international standards, while earnings expectations have also faced downward revisions this year. This creates an interesting alternative for investors - rather than owning the banks, investors can consider lending to them.
Bank credit has offered yields above bank dividend yields, with senior debt, subordinated bonds and hybrids occupying different positions in the capital structure and carrying different levels of risk. While bank dividends are discretionary and equity prices can be volatile, bond investors receive contractual interest payments, subject to the issuer's ability to meet its obligations.
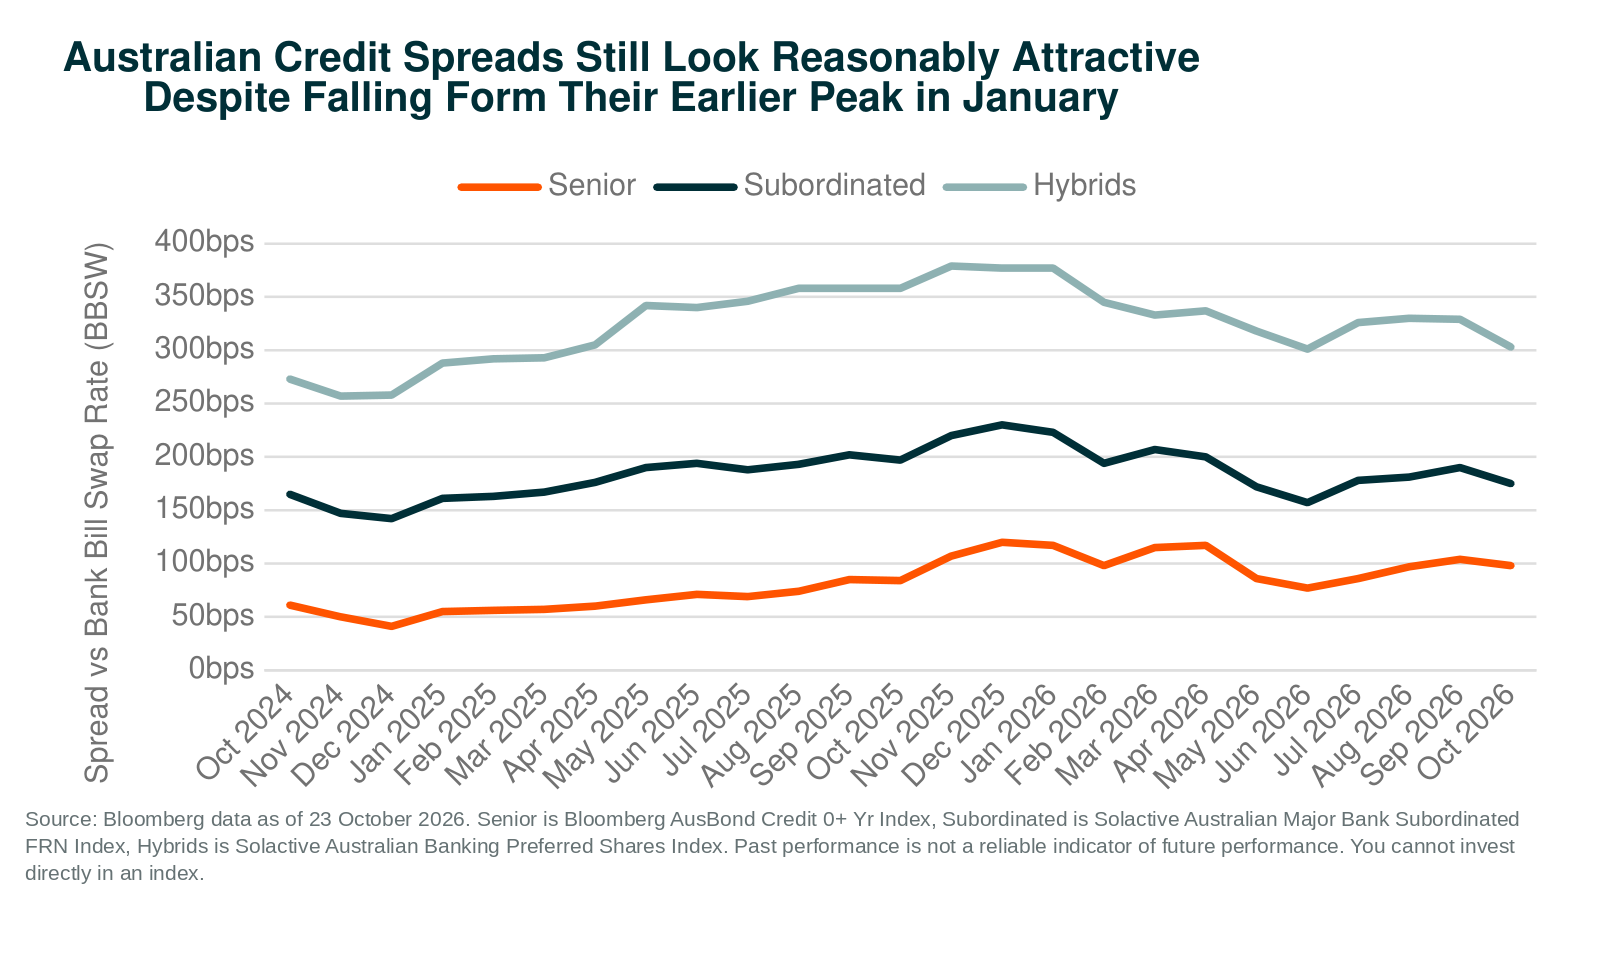
For investors seeking income without taking on the full volatility of equities, diversified bank credit can provide a compelling middle ground. For example, the Global X Australian Bank Credit ETF (BANK) combines exposure across different layers of bank credit, with its predominantly floating-rate exposure helping income respond to changes in short-term interest rates. Its relatively short duration also limits sensitivity to changes in government bond yields compared with longer-dated fixed-rate bonds. With a current running yielding of 6.3% p.a., above the major banks’ dividend yields2, it offers an attractive source of income, with distributions paid monthly.
Getting Paid To Be Patient
With bond yields now at levels not seen in years, fixed income offers investors a compelling opportunity to diversify their portfolios and capture attractive income. Australian bond ETFs have already recorded significant inflows last month, reflecting renewed interest in the asset class, while global government bonds and corporate credit offer further opportunities across markets. Combined with high-dividend equities and covered-call strategies, bonds can provide another engine of portfolio income, with different return drivers across market cycles. For investors, today's elevated starting yields present an opportunity to broaden their income toolkit and give fixed income a more meaningful role in their portfolios. Shares outperform bonds over time, but not all the time.